A limited partner in European venture funds · Switzerland
Where European exits get reinvested.
We commit our own capital to Europe's strongest venture funds, bring investors in alongside us, and build the operating machinery those funds run on.
2010
Investing in European venture since
30+
Investor events convened across Europe each year
Four
Companies built and sold by the people allocating this capital
Two ways in
Same firm. Different side of the table.
Three things, plainly. We invest in venture funds ourselves. We bring other investors into the funds we back. And we do the advisory and operating work for the funds themselves.
The capital side · For LPs
What we invest in
We are a limited partner in European venture funds and we commit from our own balance sheet. Investors who want the same exposure come in alongside us.
- Fund of fundsWe commit to European venture funds as an LP. Diversified positions in managers most individual investors cannot reach, and the way in for investors who want to sit alongside us.
- Direct investmentsConcentrated positions in companies we know through the managers backing them.
- SecondariesLP positions changing hands mid-life. Liquidity for the seller, a closed vintage for the buyer.
The client side · For GPs and founders
What we do with you
Advisory and operations for venture funds themselves, and the conversation with a founder after an exit.
- Fund formation and advisoryStructure, legal panel, policies and launch for managers raising a first or second fund.
- Outsourced fund operationsKPI collection, LP reporting, data management and the rest of the week a GP should not be spending.
- After the exitHow we think about capital once a founder has sold the company.
Why this exists
European venture has a distribution problem at both ends. The capital that should flow back into it sits in portfolios that were not built for it, and the funds worth backing are closed to almost everyone who wants in.
A founder exits and has nowhere good to put it
They know venture. They want venture. What they are offered is a balanced portfolio and a relationship manager who has never sat on a cap table.
The best funds are hard to reach and harder to leave
Access is relationship-gated and minimum tickets are high. On a ten-year horizon, liquidity only exists if someone builds the market for it.
New managers are strong investors and weak operators
A first-time GP is good at picking companies and slow at structuring a vehicle, standing up reporting and running capital calls. That work has no glamour and enormous leverage.
Track record
Built, not bought. Everything here is work we did ourselves.
Standing up a public venture fund at scale
- 01Supported the creation of a major public venture fund in EuropeFormation
- 02Built and ran its fund operationsOperations
- 03Designed its KPI collection and portfolio monitoringMonitoring
- 04Built its LP reportingReporting
- 05Set up its legal panel and external counselLegal
- 06Wrote its due diligence best practiceDiligence
- 07Designed its data managementData
Investing and ecosystem
- 08Commit to European venture funds as a limited partnerLP
- 09Set up and managed private venture fundsGP
- 10Led investment rounds into European technology companiesDirect
- 11Built and operate a proprietary database of European deep tech startupsSourcing
- 12Convene European investors at 30+ events a year across the continentNetwork
- 13Run a matchmaking platform used across the European ecosystemPlatform
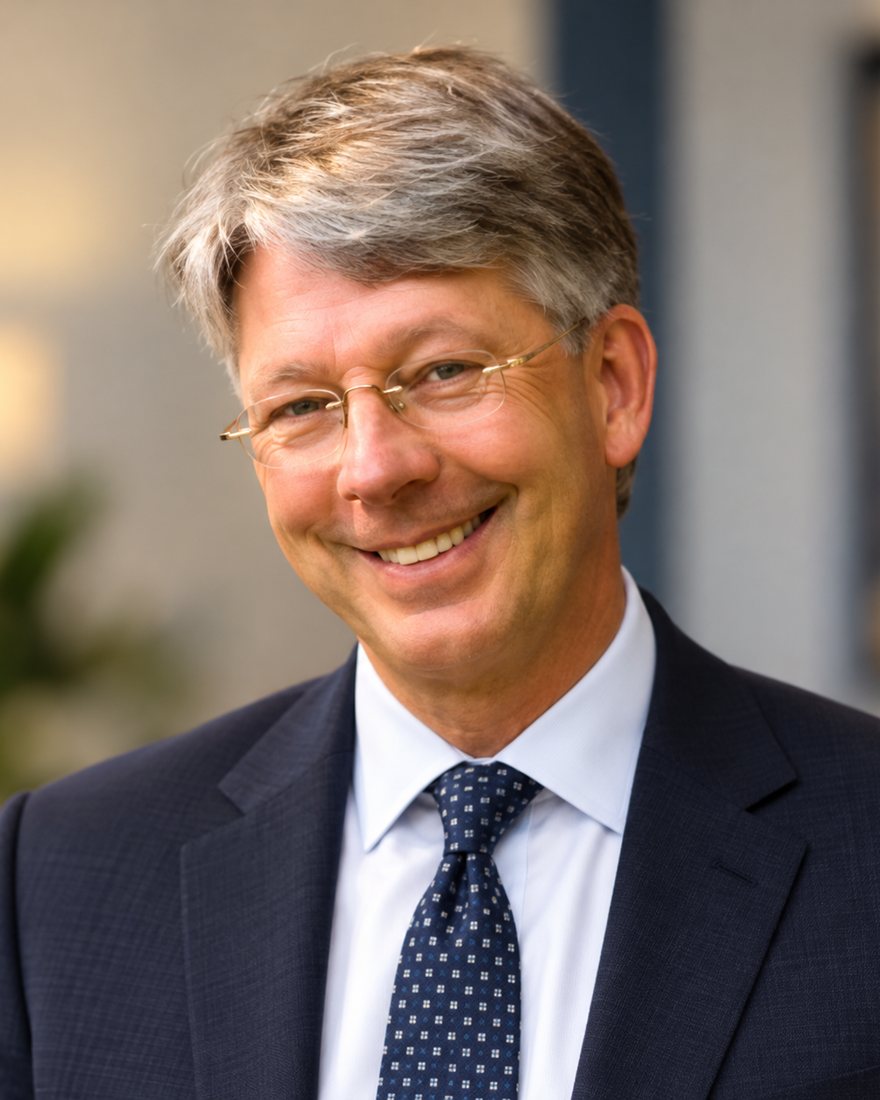
Leo Povel, Partner
Four companies built and sold. Thirty years reinvesting the proceeds.
Leo has founded, built and sold businesses across pharmaceuticals, telecommunications and maritime technology, the most recent of them last year. Since 1996 he has invested his own capital through his own holding companies, which makes him a principal rather than an adviser.
He has not stopped operating. He runs power generation in Austria, sits on the board of an AI software company in Amsterdam, and backs circular-economy businesses in the Netherlands.
- Pharmaceuticals
- Telecommunications
- Maritime technology
- Energy
- Artificial intelligence
He has sat on both sides of the conversation we have with founders. The one where you sell, and the one where you decide what happens next.
After the exit
The hardest quarter of a founder's life is the one after the money lands.
Everyone has an opinion, most of them are selling something, and the decisions made in the first twelve months set the next twenty years.
We are not a private bank and we do not want to be. We invest our own family capital into European venture, and we are happy to walk a founder through exactly how we do it.
Contact
Start a conversation.
Tell us which side of the table you are on and it reaches the right person directly.